
Quick answer
GST departmental audit support covers representation through a Section 65 audit of a registered person’s records, returns and documents, which verifies declared turnover, tax paid, refund claimed and input tax credit availed. The officer intimates the audit in Form GST ADT-01 at least 15 working days in advance, and the audit must be completed within three months of commencement, extendable by six months for reasons recorded in writing. Under Rule 101 of the CGST Rules, the taxpayer is told the findings and the reasons for them and can respond before they are finalised in Form GST ADT-02, which is usually the last chance to close a discrepancy before it becomes a show cause notice under Section 73, 74 or 74A.
Marg Tax Advisors LLP provides GST departmental audit support for businesses selected for audit under Section 65 of the CGST Act, from the first notice in Form GST ADT-01 through document verification, the objection stage before the final report, and whatever demand notice or appeal follows if the audit finding is not resolved at that stage.
An audit is not the same event as a show cause notice, and treating it that way is a common mistake. The way a business responds during the audit itself, well before any formal demand is raised, usually decides whether a discrepancy closes out as a minor reconciliation issue or turns into a contested notice later.
Who Needs GST Departmental Audit Support
- A business that has received a notice in Form GST ADT-01 intimating a departmental audit under Section 65.
- A business selected for a special audit under Section 66, directed by an officer and carried out by a nominated chartered accountant or cost accountant.
- A business preparing reconciliations and documentation ahead of an anticipated audit.
- A business that has received draft audit findings and wants to respond before the final audit report is issued.
- A business whose finalised audit report has already led to a show cause notice.
What a GST Departmental Audit Under Section 65 Actually Is
Section 65 of the CGST Act authorises the Commissioner or an officer to conduct an audit of a registered person's records, returns and other documents, to verify the correctness of declared turnover, tax paid, refund claimed and input tax credit availed, as defined in Section 2(13) of the Act. This is a different power from inspection under Section 67, which is used where the department suspects specific evasion and can extend to search and seizure, and from the general access to business premises and records under Section 71, which applies more broadly to verify compliance. A departmental audit under Section 65 is the routine, planned version of departmental scrutiny; conflating it with an inspection or a search tends to lead to an overreaction that is not always warranted.
Section 65 Departmental Audit vs Section 66 Special Audit
Both provisions authorise an examination of a taxpayer's records, but they differ in who conducts the review and when each is used.
| Section 65: Departmental Audit | Section 66: Special Audit | |
|---|---|---|
Who conducts it |
Departmental officers themselves | A chartered accountant or cost accountant nominated by the Commissioner |
When it is used |
As part of routine or risk-based audit selection | Where the case is complex or the officer believes the declared value or credit availed needs specialised examination |
Notice form |
Form GST ADT-01, at least 15 working days before the audit | Direction issued in Form GST ADT-03, with reasons recorded |
Findings recorded in |
Form GST ADT-02 | A report submitted to the Commissioner, who communicates the findings to the taxpayer in Form GST ADT-04 |
How the Audit Process Runs: Notice, Timeline and Completion
An officer intimates a Section 65 audit in Form GST ADT-01 at least 15 working days before the audit begins. Once commenced, the audit is required to be completed within three months, which the Commissioner can extend by a further six months for reasons recorded in writing. When exactly an audit is treated as having commenced, and whether one can continue after a registration is cancelled, has produced conflicting High Court decisions, so a business facing an audit that runs past the usual timeline, or one that starts after cancellation, should get that specific point reviewed rather than assuming the department's timeline is automatically valid.
During the audit, the taxpayer is required to provide the necessary facility to verify records and furnish information the officer requires. Marg Tax Advisors coordinates this stage directly, so document requests are answered on time and in the form the audit team expects, rather than creating avoidable friction that extends the audit further.
Responding to Audit Findings Before the Final Report
Under Rule 101 of the CGST Rules, once an audit is complete, the proper officer informs the taxpayer of the findings, the taxpayer's obligations, and the reasons for those findings, and the taxpayer has an opportunity to respond before the findings are finalised in Form GST ADT-02. This objection stage is often the last real opportunity to correct a discrepancy, whether through a reconciliation the audit team had not seen or a legal point on how a provision applies, before the finding hardens into a position the department carries into a formal demand. As GST departmental audit support, Marg Tax Advisors treats this stage with the same seriousness as a show cause notice reply, because in practice it often decides whether a notice is issued at all.
When an Audit Turns Into a Demand Notice
Where an audit finding is not resolved at the objection stage, it typically becomes the basis for a show cause notice under Section 73, 74 or 74A of the CGST Act. This page focuses on the audit itself, since a well-handled audit is often what keeps a matter from reaching that stage at all.
What comes after the audit
- Our Reply to GST Show Cause Notice page covers the notice stage, including the pre-notice DRC-01A intimation and the staged penalty relief available through Form GST DRC-03.
- Our GST Consultants in Delhi page covers what follows if the matter goes to appeal.
Why a Delhi Based GST Departmental Audit Support Team Matters
A departmental audit runs on the department's timeline, not the taxpayer's, and a document request can arrive with only a few days to respond. A Noida, Delhi NCR based team can attend the audit in person, respond to a document request the same day it is raised, and read a draft finding before the objection window closes, which matters more in an audit than in most other GST proceedings, since the process itself is compressed into a fixed statutory window. Marg Tax Advisors' office in Noida, Delhi NCR is built around exactly that kind of turnaround.
Who You'll Work With
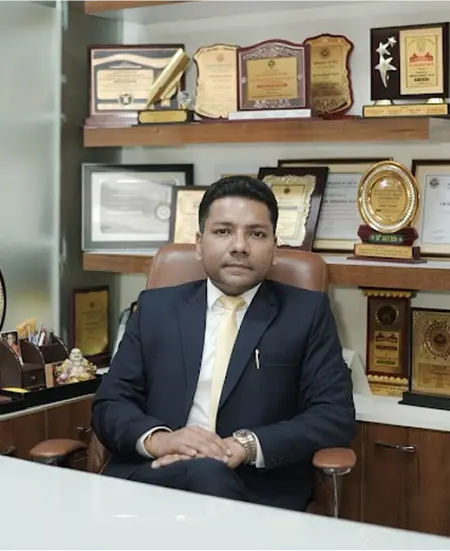
Shashank Shekhar Gupta
Founder, Chartered Accountant and Lawyer
GST departmental audit matters at Marg Tax Advisors are led by Shashank Shekhar Gupta, founder of the firm, a Chartered Accountant and a lawyer who holds a PhD on the implementation of GST in India and has conducted more than 300 seminars on GST and indirect taxation. He chairs the Goods and Services Tax Committee of the Indian Industries Association.