
Quick answer
Marg Tax Advisors LLP is a customs law practice in Delhi NCR covering both halves of customs work: getting the duty position right before goods are imported — valuation, HSN classification, exemption notifications, MOOWR, AEO and SVB — and defending that position once the department disagrees, from a Section 28 show cause notice reply through appeal before the CESTAT, High Court and Supreme Court. The practice is led from a Noida office by a Chartered Accountant and lawyer whose practice areas include customs law, free trade agreements and export/import law.
As a customs lawyer in Delhi, our team advises on the duty position before a dispute starts and represents clients once one does, working out of a Noida, Delhi NCR office under the Marg Tax Advisors LLP name. Once a dispute is actually underway, that advisory role shifts into the work of a customs litigation lawyer Delhi businesses turn to: drafting the reply, attending adjudication, and carrying the matter through appeal if the department's order does not go a client's way.
What a Customs Lawyer in Delhi Handles at Marg Tax Advisors
Customs law splits into two halves that are easy to separate on paper and hard to separate in practice: getting the duty position right before goods are imported, and defending that position once the department disagrees with it. Marg Tax Advisors works both halves:
- Concessional duty rates and exemption notifications.
- Goods valuation and classification, including Harmonized System of Nomenclature (HSN) classification.
- Anti-dumping duty and safeguard duty advisory, including levy beyond the standard five year period.
- Show cause notice replies and appeals.
- Representation before adjudicating authorities, CESTAT, High Courts and the Supreme Court.
- Support during departmental investigations, including responses to investigation allegations backed by legal precedent.
- Refund and duty drawback claims.
- MOOWR registration and compliance, Authorised Economic Operator (AEO) certification, and Special Valuation Branch (SVB) proceedings.
Customs Valuation and Classification: The Short Version
Most customs disputes start with one of two questions: what is this good worth for duty purposes, and what tariff heading does it fall under. Valuation is governed by Section 14 of the Customs Act, 1962 and the Customs Valuation (Determination of Value of Imported Goods) Rules, 2007; classification depends on the Harmonized System of Nomenclature, and a wrong HSN code can change the applicable duty rate, trigger an anti-dumping duty that would not otherwise apply, or block an exemption notification a client was relying on. We review both before goods move, not just after a dispute has already been raised, because under Sections 111 to 114 of the Customs Act, 1962, a misdeclaration on either point can turn a paperwork question into a confiscation and penalty matter within months.
Go deeper on valuation
- For the full detail on how a valuation dispute, an SVB reference or a classification challenge actually runs, see our dedicated Customs Valuation Consultant page.
Common Customs Disputes We Handle
- Valuation disputes where the department rejects the declared transaction value and loads the assessable value upward.
- Classification disputes over the correct HSN heading and the duty rate or exemption notification that follows from it.
- Show cause notices alleging misdeclaration of description, quantity or value, with confiscation and penalty proposed under Sections 111 to 114.
- Anti-dumping or safeguard duty applicability disputes, including cases where a duty is sought to be applied beyond its original five year term.
- Refund and duty drawback claims rejected or delayed by the department.
- Summons and document requests from the Directorate of Revenue Intelligence (DRI) or the department's Special Intelligence and Investigation Branch (SIIB) under Section 108 of the Customs Act, 1962, which gives the department power to record statements and call for documents during an investigation.
- Denial of MOOWR, AEO or SVB benefits, or delays in processing an application already filed.
Customs Litigation Lawyer Delhi: Show Cause Notices, Appeals and Tribunal Representation
A customs dispute usually begins with a show cause notice under Section 28 of the Customs Act, 1962, alleging short levy, non-levy or an erroneous refund. From there, the matter can move through several forums:
| Stage & Forum | Legal Basis | What Happens |
|---|---|---|
Stage 1
Adjudicating Authority |
Section 28, Customs Act, 1962 | Show cause notice for short levy, non-levy or erroneous refund, followed by an adjudication order |
Stage 2
Commissioner (Appeals) |
Section 128, Customs Act, 1962 | First appeal against the adjudication order |
Stage 3
CESTAT |
Section 129A, Customs Act, 1962 | Appeal against the Commissioner (Appeals) order; CESTAT's Principal Bench sits in Delhi |
Stage 4
High Court or Supreme Court |
Sections 130 and 130E, Customs Act, 1962 | Substantial questions of law go to the High Court; matters on rate of duty or valuation for assessment go directly to the Supreme Court |
We represent clients at adjudication and carry the matter through appeal where needed; because CESTAT's Principal Bench sits in Delhi, our team can attend hearings, track cause lists and respond to tribunal directions without the delay of travel.
Where a matter starts as a departmental investigation rather than a straightforward show cause notice, our support covers responding to summons issued under Section 108, preparing a client for a statement recording, and building the factual and legal response to the allegations raised, backed by the relevant precedent. That work usually runs alongside, not instead of, the underlying duty or classification dispute it grew out of.
Go deeper on a show cause notice
- For the specific mechanics of drafting and filing a show cause notice reply itself, including response timelines and what a strong reply covers, see our dedicated Customs Show Cause Notice Reply page.
MOOWR: Manufacture and Other Operations in a Bonded Warehouse
The Manufacture and Other Operations in Warehouse (No. 2) Regulations, 2019, issued under Section 65 of the Customs Act, 1962, let a business import capital goods and raw materials into a bonded warehouse and defer customs duty until the finished goods leave the warehouse, with no duty at all if the output is exported.
We assist with the registration application, document preparation, and responses to department queries during registration, representation at the site visit, and monthly return filing once the unit is operational.
Authorised Economic Operator (AEO) Certification Support
AEO certification, built on the World Customs Organization's SAFE Framework, gives importers and exporters faster clearances, fewer physical examinations and reduced bank guarantee requirements once granted. The application itself is document heavy: security standards have to be reviewed, a technical annexure prepared for the relevant tier, and the business needs to be ready for physical verification by the department. Marg Tax Advisors supports clients through each of these steps rather than only the final filing.
Special Valuation Branch (SVB) Proceedings for Related Party Imports
When an importer buys from a related foreign entity, whether a parent company, subsidiary or group entity, Rule 3(3) of the Customs Valuation Rules, 2007 requires the department to examine whether that relationship influenced the declared price. That examination is handled by the Special Valuation Branch under the procedure set out in Circular 5/2016-Customs, which governs the SVB questionnaire, the applicable timelines and the abolition of the earlier extra duty deposit requirement. We prepare the SVB submission, respond to department queries on the relationship and pricing, and represent clients at the SVB hearing.
Why a Delhi Based Customs Lawyer Matters
Customs enforcement and adjudication in India runs heavily through Delhi. That means shorter turnaround on filing, faster response to a hearing notice, and direct familiarity with how the Delhi forums actually run a matter for our team, rather than working from precedent alone.
CESTAT Principal Bench
The tribunal's Principal Bench sits in Delhi, so hearings, cause lists and tribunal directions are handled locally.
CBIC
The Central Board of Indirect Taxes and Customs is headquartered in the city, where customs policy and circulars originate.
DRI
The Directorate of Revenue Intelligence is also headquartered in Delhi, which is where many investigations and summons begin.
IGI Airport in Delhi is also one of India's busiest points of entry for high value and high scrutiny cargo, which is where many valuation and classification disputes originate in the first place, so working out of Delhi keeps us close to where these matters actually start.
Who You'll Work With
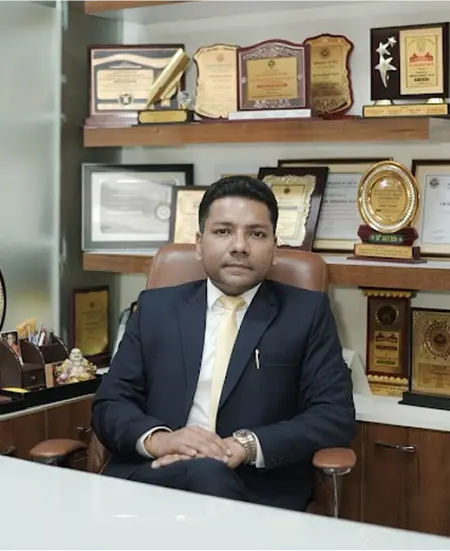
Shashank Shekhar Gupta
Founder · Chartered Accountant & Lawyer
Customs matters at Marg Tax Advisors are led by Shashank Shekhar Gupta, founder of the firm, a Chartered Accountant and a lawyer whose practice areas include customs law, free trade agreements and export/import law directly, alongside indirect taxation more broadly. He chairs both the International Trade Law Committee and the Goods and Services Tax Committee of the Indian Industries Association, and before founding Marg Tax Advisors he worked with Deloitte and other consulting practices.