
Quick answer
Marg Tax Advisors LLP is a Noida, Delhi NCR practice acting as GST consultants for businesses across the full cycle: registration under Sections 22 and 24 of the CGST Act, monthly and annual returns, show cause notice replies under Sections 73, 74 and 74A, refund claims for exporters and inverted duty structures, and appeals through the Appellate Authority, GSTAT, the High Court and the Supreme Court. Lawyers and chartered accountants work the same file, because a GST notice reply is usually won on the reconciliation behind it, not the legal argument alone.
As a GST advisor in Delhi, we pair lawyers with chartered accountants, because most GST disputes turn on both a legal question and a reconciliation question, and separating the two across different advisors is usually where a case loses time or loses ground.
Businesses come to us as a GST litigation lawyer in Delhi once a notice has already landed, as a GST refund consultant when a claim needs to be filed or defended against a deficiency memo, and as a GST appeal consultant when an adjudication order needs to be challenged before the Appellate Authority or GSTAT.
What a GST Consultant in Delhi Handles at Marg Tax Advisors
- New GST registration, amendments, and voluntary registration where it helps a client's input tax credit position.
- Monthly and quarterly return filing support: GSTR-1, GSTR-3B, and the annual GSTR-9 and GSTR-9C reconciliation.
- Show cause notice replies, demand disputes and litigation under Sections 73, 74 and 74A of the CGST Act.
- Refund claims for exporters, inverted duty structures and excess balance in the electronic cash ledger.
- Appeals before the Appellate Authority and the GST Appellate Tribunal (GSTAT), and writ remedies before the High Court where warranted.
- Cancellation and revocation of registration, and e-way bill or e-invoicing compliance queries.
GST Registration in Delhi: Thresholds and What Triggers It
Registration under Section 22 of the CGST Act is based on aggregate turnover, and the threshold differs by category and by state:
| Category | Standard Category States | Special Category States |
|---|---|---|
Supply of goods |
₹40 lakh aggregate turnover | ₹20 lakh aggregate turnover |
Supply of services |
₹20 lakh aggregate turnover | ₹10 lakh aggregate turnover |
Composition scheme (goods) |
Up to ₹1.5 crore aggregate turnover | Up to ₹75 lakh aggregate turnover |
Separately, Section 24 makes registration mandatory regardless of turnover for certain categories: anyone making a taxable interstate supply, casual taxable persons, persons liable to pay tax under reverse charge, e-commerce operators, most suppliers selling through an e-commerce operator, input service distributors, non-resident taxable persons, and persons required to deduct tax under Section 51 or collect it under Section 52. As GST registration consultants in Delhi, the first thing we check is not the turnover threshold in isolation but whether one of these Section 24 categories applies, since that decides whether registration is optional or mandatory regardless of size.
Ongoing GST Compliance: Returns, E-Invoicing and E-Way Bills
Once registered, a business normally files GSTR-1 for outward supplies and GSTR-3B as the summary return and payment challan, on a monthly or quarterly cycle depending on turnover and the scheme chosen, plus the annual GSTR-9. Above a turnover threshold, GSTR-9C, a reconciliation statement between the annual return and audited financial statements, is also required; since the 2021 amendment omitted Section 35(5), this is now self-certified by the taxpayer rather than certified by an external CA or CMA, a change several competitor pages still describe as a mandatory third-party GST audit.
E-invoicing is mandatory above a turnover threshold that has been lowered more than once since it was introduced; e-way bills are required under Rule 138 for most movements of goods above ₹50,000 in value, with some states setting a higher threshold for intra-state movement. Both figures move, so Marg Tax Advisors confirms the current threshold against the latest CBIC notification before advising a client.
GST Litigation Lawyer in Delhi: Notices, Demands and Adjudication
A return filing service and a GST litigation lawyer in Delhi are not the same thing, and the difference matters once a notice arrives. Before a formal notice is even issued, an officer can send an intimation in Form GST DRC-01A under Rule 142(1A), setting out the tax, interest and penalty the department believes is due; replying at this pre-notice stage, with the reconciliation to back it up, can close a matter before it becomes a formal dispute at all.
Where a show cause notice is issued anyway, it falls under Section 73 of the CGST Act where there is no allegation of fraud, and under Section 74 where there is; for tax periods from FY 2024-25 onward, Section 74A now provides a common time limit for both, replacing the separate 73/74 limitation regime for those periods, while 73 and 74 continue to govern earlier periods already under notice or assessment. A reply that does not track which provision actually applies to the period in question is a common, avoidable weakness in a GST defence.
Marg Tax Advisors drafts the reply, represents clients at personal hearing before the adjudicating authority, and carries a matter into appeal where the order does not hold up. A departmental audit under Section 65, or a special audit under Section 66 directed by an officer where the case is complex, often runs alongside or ahead of this litigation, and we prepare clients for that stage too.
GST Refund Consultant in Delhi: When a Claim Applies
Refund claims usually arise from an inverted duty structure, an excess balance in the electronic cash ledger, a deemed export, or an export of goods or services. For a domestic inverted duty structure or cash ledger refund, the claim runs under a separate Rule 89(5) formula rather than the export formula under Rule 89(4), and is filed on the same RFD-01 form through the GST portal.
As a GST refund consultant in Delhi, we also handle the position where a claim has already been rejected or partly sanctioned: the two-year limitation period under Section 54 excludes the time a claim sits with the department over a deficiency memo under Rule 90(3), and a rejected claim can still be carried into appeal rather than treated as final.
Go deeper on export refunds
- Exporters have their own detailed process; see our dedicated GST Refund Process for Exporters page for the full route, timelines and what to do if a claim is delayed or rejected.
GST Appeal Consultant: The GSTAT Appeal Ladder
Where an adjudication order does not resolve a dispute favourably, a GST appeal consultant takes the matter through a fixed sequence:
| Stage & Forum | Legal Basis | What Happens |
|---|---|---|
Stage 1
Appellate Authority |
Section 107, CGST Act | First appeal against an adjudication order; requires a pre-deposit of 10 percent of the disputed tax amount |
Stage 2
GST Appellate Tribunal (GSTAT) |
Section 112, CGST Act | Second appeal; GSTAT is now operational and accepting filings, with its own additional pre-deposit requirement on top of the Section 107 deposit |
Stage 3
High Court |
Section 117, CGST Act | Appeal on a substantial question of law arising from a GSTAT order |
Stage 4
Supreme Court |
Section 118, CGST Act | Further appeal from a High Court order |
An appeal to the Appellate Authority under Section 107 normally has to be filed within three months of the order, though Section 107(4) allows the Appellate Authority to condone a further delay of up to one month where sufficient cause is shown; beyond that window, the appeal is generally time-barred regardless of the merits. The exact GSTAT pre-deposit percentage and cap have been revised before, so we confirm the current figure at the time of filing rather than relying on a fixed number from an earlier round of amendments.
Why a GST Advisor and Lawyer Team Matters
One team, start to finish
Registration, returns, notices and appeals handled by one team, so a client's history does not need to be re-explained every time a matter escalates.
Law and reconciliation together
A combined lawyer and chartered accountant perspective on the same file, which matters because a GST notice reply is usually won on the specific reconciliation behind it, not the legal argument alone.
Delhi forums within reach
Direct familiarity with Delhi forums: the Appellate Authority, GSTAT's Principal Bench and the Delhi High Court are all reachable without the delay of travel.
Current on recent changes
Including the self-certified GSTR-9C position, the Section 74A demand framework and GSTAT's operational status, rather than describing the pre-2021 or pre-2024 position by default.
Who You'll Work With
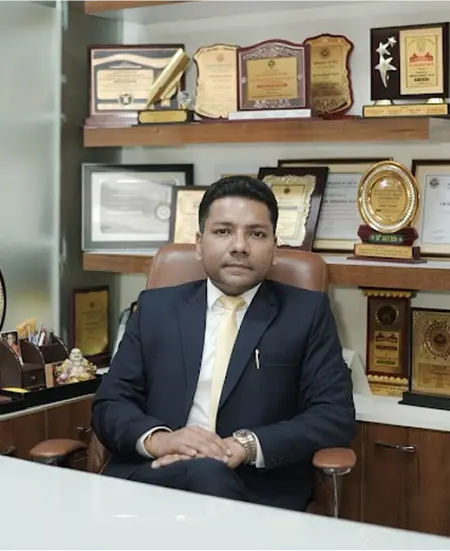
Shashank Shekhar Gupta
Founder · Chartered Accountant & Lawyer
GST matters at Marg Tax Advisors are led by Shashank Shekhar Gupta, founder of the firm, a Chartered Accountant and a lawyer who holds a PhD on the implementation of GST in India compared against VAT systems in other countries, and has conducted more than 300 seminars on GST and indirect taxation. He chairs the Goods and Services Tax Committee of the Indian Industries Association, alongside its International Trade Law Committee.