
Quick answer
Marg Tax Advisors LLP is a customs valuation consultant for importers in India, working on transaction value under Section 14 of the Customs Act, 1962 and the Customs Valuation Rules, 2007. Where the buyer and foreign seller are related under Rule 2(2), the declared price is not accepted automatically: the importer files Annexure A on the first related party import, and a Special Valuation Branch reference brings the Annexure B questionnaire with a 60-day response window. Circular 5/2016-Customs abolished the routine Extra Duty Deposit, and a 5 percent deposit now applies only where Annexure B goes unanswered, typically for three months. An SVB investigation order, once approved, applies at all Indian ports without a fixed expiry.
Marg Tax Advisors LLP works as a customs valuation consultant for importers whose declared transaction value is questioned by the department, whether that scrutiny comes from a routine assessment or from a related party relationship that puts the import into Special Valuation Branch (SVB) review. Valuation is where a large share of customs disputes actually starts, and getting the transaction value position right before goods move is usually less expensive than defending it after a show cause notice has already been issued.
Customs valuation is governed by Section 14 of the Customs Act, 1962, which fixes the transaction value, the price actually paid or payable for the goods, as the primary basis for assessment, adjusted and tested against the Customs Valuation (Determination of Value of Imported Goods) Rules, 2007. Where the buyer and the foreign seller are related, that transaction value does not get accepted automatically; it has to survive a specific examination under the Customs Valuation Rules before the department will assess on that basis.
What Our Customs Valuation Consultant Team Handles
- Transaction value review under Section 14 before goods are imported, including additions required under the Customs Valuation Rules for royalties, licence fees and assists.
- Related party assessment and the initial Annexure A declaration on a first related party import.
- SVB questionnaire responses and representation through Annexure B and the investigation that follows.
- Extra Duty Deposit disputes, including cases where a deposit has been imposed for non-response rather than as a matter of course.
- Provisional assessment finalisation once an SVB investigation order is issued.
- Appeals where a valuation order does not go a client's way, in coordination with our customs litigation team.
Transaction Value Under Section 14: The Short Version
Section 14 of the Customs Act, 1962 treats the transaction value, the price actually paid or payable for goods when sold for export to India, as the starting point for assessment, provided the buyer and seller are not related, or, where they are related, provided the relationship did not influence the price. The Customs Valuation Rules, 2007 set out what has to be added to that price, such as royalties and licence fees connected to the imported goods and payable as a condition of sale, and the grounds on which the department can reject a declared value and move to the sequential valuation methods the Rules prescribe instead. Marg Tax Advisors reviews this position before goods move, since a transaction value built on the wrong assumptions can unravel months later as a valuation dispute or an SVB referral that a cleaner declaration would have avoided.
The SVB Process: Annexure A, Annexure B and the Extra Duty Deposit
Once a related party import is identified, the process runs through a fixed sequence, and where an importer sits in that sequence changes what representation actually involves.
| Stage | What Happens |
|---|---|
Initial declarationAnnexure A |
The importer files Annexure A, disclosing the relationship and the basis on which the declared price is said to be unaffected by it, on the first related party import |
SVB referral and questionnaireAnnexure B, 60 days |
Where the case is referred to SVB, the department issues the detailed Annexure B questionnaire, and the importer has 60 days to respond with supporting evidence |
Extra Duty DepositOnly on non-response |
Circular 5/2016-Customs abolished the earlier standard Extra Duty Deposit that used to apply to provisional assessments as a matter of course. A 5 percent deposit still applies, but only as a consequence of failing to respond to Annexure B within the time allowed, and typically for a 3-month period |
Investigation and orderAll Indian ports |
SVB examines whether the relationship influenced the price and issues an investigation order with the approval of the Principal Commissioner or Commissioner, which then applies at all Indian ports without a fixed expiry |
When SVB Registration Is Not Required
Not every related party import needs a full SVB reference. Getting this exemption analysis right at the outset avoids opening an SVB reference an importer did not actually need to file.
Samples and prototypes
Sample and prototype imports are ordinarily kept outside SVB scrutiny.
Nil or fully exempt duty
Imports where duty is nil or fully exempt do not ordinarily need a reference.
Low value transactions
Low value imports are ordinarily kept out of SVB scrutiny as well.
If a Valuation or SVB Order Does Not Go Your Way
An adverse SVB or valuation order can be appealed through the same forums that hear any other customs dispute, starting with the Commissioner (Appeals) and moving to CESTAT where needed. This page focuses on getting the valuation and SVB position right in the first place, and on the SVB process itself rather than the appeal mechanics that follow a finding.
Related reading
- Our Customs Lawyer in Delhi page covers the appeal ladder in full, including the drafting and the tribunal representation.
- Where the dispute arrives as a notice rather than an assessment, our Customs Show Cause Notice Reply page covers the reply and the adjudication hearing.
Why a Delhi Based Customs Valuation Consultant Matters
SVB references and valuation disputes for importers across North India are frequently coordinated through Delhi, and CESTAT's Principal Bench, where a valuation appeal ultimately lands if it goes that far, also sits in the city. Marg Tax Advisors keeps that coordination and any resulting appeal within one team rather than handing the file off partway through.
Who You'll Work With
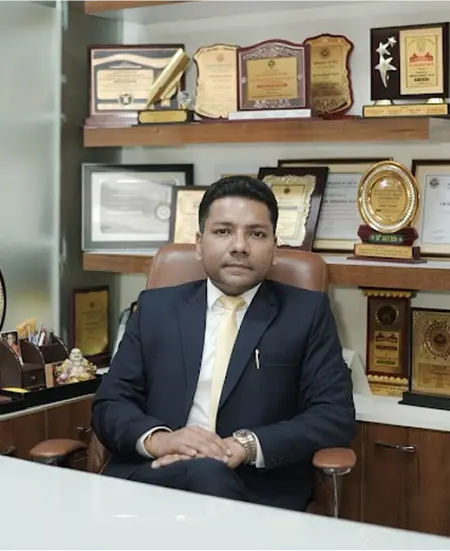
Shashank Shekhar Gupta
Founder, Chartered Accountant and Lawyer
Customs valuation and SVB work at Marg Tax Advisors is led by Shashank Shekhar Gupta, founder of the firm, a Chartered Accountant and a lawyer who chairs the International Trade Law Committee of the Indian Industries Association.