
Quick answer
Under Section 16 of the IGST Act, exports and supplies to an SEZ developer or unit for authorised operations are zero-rated, so an exporter recovers the GST either by paying IGST and claiming it back, or by exporting under a Letter of Undertaking on Form RFD-11 and claiming accumulated input tax credit. For goods exported with IGST, the shipping bill itself is the refund application under Rule 96 and the refund triggers automatically once shipping bill, EGM and GSTR data match. Under the LUT route, Form RFD-01 is filed and the amount is calculated under Rule 89(4), within two years of the relevant date. After filing, RFD-02 acknowledges, RFD-04 can release up to 90 percent provisionally, and the final order is due within 60 days, after which interest runs under Section 56.
Exports are treated as zero-rated supplies under Section 16 of the IGST Act, which means an exporter should not end up bearing GST as a cost of goods or services sold outside India. In practice, getting that tax back means going through the GST refund process for exporters correctly, since a mismatched shipping bill entry or an incomplete application is the most common reason a claim stalls. Marg Tax Advisors advises exporters on filing correctly in the first place, and represents them when a claim is delayed, questioned or rejected, which is the part of this process most guides skip over.
What Counts as a Zero-Rated Supply
Under Section 16 of the IGST Act, two categories qualify for zero rating: export of goods or services out of India, and supply of goods or services to a Special Economic Zone (SEZ) developer or SEZ unit for authorised operations. Zero rated does not mean the transaction falls outside GST altogether; it means the exporter is entitled to either not pay tax on the supply or to recover the tax paid on it, so the credit chain does not silently become a cost.
The Two Routes for a GST Refund on Exports
An exporter has to choose between two routes at the time of export, and the GST refund process for exporters looks different depending on which one is chosen.
| Route 1: Export With IGST Payment | Route 2: Export Under LUT, No IGST Paid | |
|---|---|---|
What you pay upfront |
IGST is paid at the time of export and claimed back as a refund | No IGST is paid; input tax credit accumulates instead |
What you file |
For goods, the shipping bill itself is treated as the refund application under Rule 96; for services, Form RFD-01 is filed separately | Form GST RFD-11 (LUT) upfront, then Form RFD-01 to claim the accumulated ITC refund |
How the refund is triggered |
Automatically, once the shipping bill, Export General Manifest and GSTR-1 or GSTR-3B data match through the ICEGATE-GSTN interface | Manually, by filing RFD-01 with the refund calculated under Rule 89(4) |
Typically suits |
Exporters comfortable funding IGST upfront and wanting a faster, largely automated refund on goods | Exporters who would rather not fund IGST upfront, or who export services where the automated goods route does not apply |
Most exporters who do not want to fund IGST upfront file a Letter of Undertaking on Form RFD-11 at the start of the financial year, which then covers all their zero-rated supplies for that year without needing a fresh LUT for every shipment.
Filing a Refund Claim Under the LUT Route
Where IGST has not been paid, the refund is of unutilised input tax credit, and it has to be claimed by filing Form RFD-01 on the GST portal. The refund amount is not simply the ITC balance in the ledger; it is calculated under Rule 89(4) of the CGST Rules using the formula: refund amount equals turnover of zero-rated supply of goods and services multiplied by Net ITC, divided by adjusted total turnover. Getting this formula's inputs right, particularly what counts as turnover for the period and what is excluded from Net ITC, is one of the more common points where an otherwise valid claim gets reduced or queried.
The application needs to be filed within two years of the relevant date, which for goods is generally the date on which the ship or aircraft carrying the goods leaves India, or the date the goods pass the frontier for export by land, and for services is generally tied to the date payment was received in convertible foreign exchange. Missing this window closes the claim entirely, regardless of how strong the underlying case is.
This Rule 89(4) formula is specific to the export refund route covered on this page. An exporter who also has an inverted duty structure claim on domestic supplies should keep that calculation separate, since it runs under the distinct Rule 89(5) formula rather than Rule 89(4).
Documents an Exporter Needs to Have Ready
For goods
Import Export Code (IEC), shipping bill, tax invoice, Export General Manifest (EGM) filed by the carrier, and Bank Realisation Certificate (BRC) evidencing receipt of export proceeds.
For services
The Letter of Undertaking or bond, the underlying service agreement, tax invoices carrying the correct SAC code, and a Foreign Inward Remittance Certificate (FIRC) or BRC evidencing payment received.
For both
Correctly filed GSTR-1 (with exports reported in Table 6A) and GSTR-3B for the relevant period, since a mismatch between these returns and the shipping bill or invoice data is one of the most common reasons a claim is queried before it is even reviewed on the merits.
What Happens After You File: The Post-Filing Timeline
Once a refund application is filed, it moves through a fixed sequence of statutory checkpoints, each with its own form number and deadline.
| Stage | What Happens |
|---|---|
AcknowledgementRFD-02 |
Issued once the application is found complete, generally within about 15 days of filing |
Provisional refundRFD-04 |
Up to 90 percent of the eligible amount released provisionally, within 7 days of acknowledgement, for exporters not flagged under the applicable risk parameters |
Deficiency memoRFD-03 |
Issued if the application is incomplete; the original application is then treated as not filed, and a corrected application has to be filed afresh |
Show cause noticeRFD-08 |
Issued if the department proposes to reject the claim in whole or in part, with a reply due on Form RFD-09 |
Final order and paymentRFD-06, RFD-05 |
Sanctions or rejects the balance amount; the standard statutory limit for disposing of the application is 60 days from the date of a complete application |
Interest on delaySection 56 |
If the refund is not paid within 60 days, interest is payable under Section 56 of the CGST Act, generally at 6 percent per annum from the date immediately after that 60-day period |
Common Reasons a GST Refund Claim Gets Delayed or Reduced
- A mismatch between the shipping bill, the Export General Manifest and the export turnover declared in GSTR-1 or GSTR-3B, which is checked automatically before a goods refund is released.
- An incorrect port code or a discrepancy between the invoice value and the shipping bill value, which is one of the most common reasons an otherwise valid claim gets flagged for manual review.
- Net ITC figures in the RFD-01 application that do not reconcile with the electronic credit ledger for the relevant period.
- Claiming a refund on ineligible input tax credit, whether because a supplier has not filed their own return or because the credit relates to a blocked category under Section 17(5) of the CGST Act.
- Filing the LUT late, or letting it lapse between financial years, so that a shipment made in the gap ends up outside LUT cover even though the exporter intended to ship without paying IGST.
What to Do If Your GST Refund Claim Is Delayed, Queried or Rejected
This is the part of the GST refund process for exporters that most guides stop short of, and it is usually where an exporter actually needs professional help rather than a checklist. A deficiency memo on Form RFD-03 means the department has found the application incomplete; because the original application is then treated as not filed, a corrected application has to be filed afresh, and the proviso to Rule 90(3) of the CGST Rules expressly excludes the period between the original filing and the issue of the deficiency memo from the two-year computation, so the limitation clock is protected for that interval. Where the department proposes to reject a claim outright, a show cause notice on Form RFD-08 is issued, and a reasoned reply on Form RFD-09, addressing the specific ground raised, needs to be filed within the notice's own deadline.
If the final order still rejects the claim in whole or in part, it can be appealed to the Appellate Authority under Section 107 of the CGST Act, and from there to the GST Appellate Tribunal (GSTAT). GSTAT is now operational and accepting filings, including the backlog of appeals against pre-existing orders that had built up while the Tribunal was being constituted, for which the filing window ran to 30 June 2026. An appeal to GSTAT carries its own pre-deposit requirement under Section 112 of the CGST Act, in addition to the pre-deposit already made for the first appeal under Section 107.
A refund that simply sits past the 60-day statutory window without any order at all is not something an exporter has to accept quietly either: interest becomes payable under Section 56 of the CGST Act at 6 percent per annum, rising to 9 percent where the refund arises from an order in appeal, and that entitlement is worth raising with the department directly rather than waiting indefinitely.
GST Refunds for SEZ Supplies
Supplies to an SEZ developer or SEZ unit for authorised operations are zero rated in the same way exports are, and follow a broadly similar refund process, with the refund application filed by the supplier under Rule 89, after the specified officer of the Zone endorses receipt of the goods or services for authorised operations. Where a supplier to an SEZ unit does end up paying IGST, the mechanics mirror the export-with-IGST-payment route described above, though the SEZ specific endorsement requirements on the invoice and the involvement of the SEZ authority are worth confirming before filing, since they differ from a standard export shipment.
How Marg Tax Advisors Helps with GST Refunds for Exporters
Marg Tax Advisors supports exporters through the full GST refund process, not only the initial filing: reviewing LUT and RFD-01 applications before they go in, responding to deficiency memos and show cause notices, and taking a rejected refund order into appeal where the underlying claim is sound. Because the firm also handles customs matters, including shipping bill and Export General Manifest issues that frequently sit behind a stalled IGST refund, GST refund questions rarely need to be handed off to a second advisor partway through.
Related reading
- For the firm's full GST practice, including registration, litigation and departmental audit support, see our GST Consultants in Delhi page.
- If a refund dispute has already become a notice, see our Reply to GST Show Cause Notice page.
Who You'll Work With
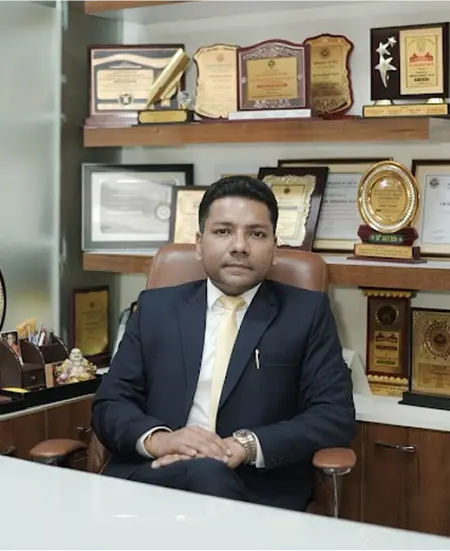
Shashank Shekhar Gupta
Founder, Chartered Accountant and Lawyer
GST refund and litigation matters at Marg Tax Advisors are led by Shashank Shekhar Gupta, founder of the firm, a Chartered Accountant and a lawyer who holds a PhD on the implementation of GST in India compared against VAT systems in other countries, and chairs the Goods and Services Tax Committee of the Indian Industries Association alongside its International Trade Law Committee.